Medicare Open Enrollment: What to Check for a Parent Living Alone
Medicare open enrollment runs from October 15 through December 7, 2026, for coverage that begins January 1, 2027. If you are the adult child who handles this every year, you already know it arrives as a pile of envelopes on your parent’s kitchen counter and a vague sense that something should probably be looked at.
Most years, the honest answer is that nothing needs to change. That is a fine outcome. But you only get to that answer by checking, and a parent living alone has a few things worth checking that a married couple with a caregiver in the house does not.
We should say clearly what this is and is not. Vital Link does not sell insurance, we have no relationship with any Medicare plan, and we earn nothing from what you decide. This is the checklist we would give a friend, plus the free counseling programs that exist precisely so nobody has to take advice from a salesperson.
If the review turns into a broader conversation about how your parent is doing at home, we are happy to talk that through with no pressure, and you can start with our overview of medical alert systems across the Bay Area.
The Medicare Open Enrollment Dates You Need
Medicare open enrollment runs October 15 through December 7, 2026, and any change made in that window takes effect January 1, 2027. Miss it and, with limited exceptions, your parent is in their current plan for the year.
During that window a person can switch from Original Medicare to a Medicare Advantage plan, switch from Medicare Advantage back to Original Medicare, move from one Advantage plan to another, and join, drop, or change a Part D drug plan. That is a wide set of doors, which is exactly why it feels overwhelming.
There is a second, narrower window worth knowing. From January 1 through March 31, someone already enrolled in a Medicare Advantage plan can make one change, either to a different Advantage plan or back to Original Medicare with a drug plan. So a January discovery is not a catastrophe. The full rules live on the Medicare enrollment periods page.
💡 The one thing to do first. Medicare open enrollment for the 2027 plan year runs October 15 to December 7, 2026. Before comparing anything, find the Annual Notice of Change that your parent’s plan mailed in September. It lists every change coming next year, and it answers most of the questions people spend hours searching for.
Start With the Notice That Arrived in September
The Annual Notice of Change is the single most useful document in the whole pile, and it is the one most likely to have been thrown out. Plans are required to send it by the end of September, and it lays out, side by side, what the plan covers this year and what it will cover next year.
Look for four things in it. What is happening to the monthly premium and the deductible. What is happening to copays for primary care, specialists, and hospital stays. What is changing on the drug list. And what is changing in the supplemental benefits, the dental, vision, hearing, transportation, and over the counter allowances that vary enormously from plan to plan.
If it is gone, do not go hunting through the recycling. Call the member services number on the back of the insurance card and ask them to send another copy, or read it in the plan’s online member portal. It is a five minute phone call.
One caution while you are in the mail pile. Enrollment season is peak season for fraud, and a parent living alone is the exact target. Nobody from Medicare will call to ask for a Medicare number, a bank account, or a credit card. Our guide to Medicare scams targeting seniors covers the current scripts.
Confirm the Doctors and the Pharmacy Are Still In Network
Networks change every January, and a plan can drop a medical group or a hospital system without your parent hearing about it until they show up for an appointment. For a parent living alone, losing an established doctor is not just a billing problem. It is the loss of the person most likely to notice a change in them.
Make a list of every provider they actually see: primary care, cardiologist, ophthalmologist, podiatrist, physical therapist, and the hospital they would want to be taken to. Then verify each one directly with the plan for the 2027 year, not from a directory printed last spring. Call the doctor’s billing office too and ask which plans they are contracted with next year. The two answers do not always match, and when they disagree it is worth a second call.
Do the same for the pharmacy. Preferred pharmacy status changes yearly, and the same drug at the same plan can cost noticeably more at a non-preferred counter. If your parent walks to the pharmacy on the corner, that convenience is part of the calculation. Someone who has to drive across town for a prescription in the rain is a different risk than someone who does not.
Doing this from another state? Call our Oakland office at (510) 338-3466 if the review has you worried about how your parent is managing at home, or book an in-home visit.
Check the Drug List Against What They Actually Take
The formulary is where the real money hides. Plans move drugs between tiers, add prior authorization requirements, and drop medications entirely from one year to the next, and a single change can shift a household budget by hundreds of dollars.
Do not work from memory or from a list your parent recites. Go to the cabinet, line up the actual bottles, and write down the drug name, the dose, and the quantity. Then run that exact list through the Medicare Plan Finder, which compares total annual cost across the plans available in their ZIP code. Total annual cost is the number that matters, not the monthly premium. A cheaper premium with a worse drug list is frequently the more expensive plan.
While the bottles are out, take thirty seconds for a different question. Is anything expired, is anything duplicated, and is there a system that keeps the doses straight? Medication mistakes are a leading cause of the dizziness and falls that put an older adult on the floor, and the National Institute on Aging has a straightforward guide to reviewing them.
Look at the Benefits That Support Living at Home
Supplemental benefits are where Medicare Advantage plans differ most from each other, and for a parent living alone they can matter more than a copay difference. These benefits vary by plan and by year, so read your parent’s own documents rather than trusting a summary anyone wrote, including this one.
The categories worth scanning for are transportation to medical appointments, meal delivery after a hospital stay, in-home support hours, dental and vision and hearing coverage, fitness programs, and over the counter or flexible spending allowances. Hearing coverage deserves particular attention. A parent who cannot hear the phone will not answer it when you call to check in, and that changes everything about how a family stays connected.
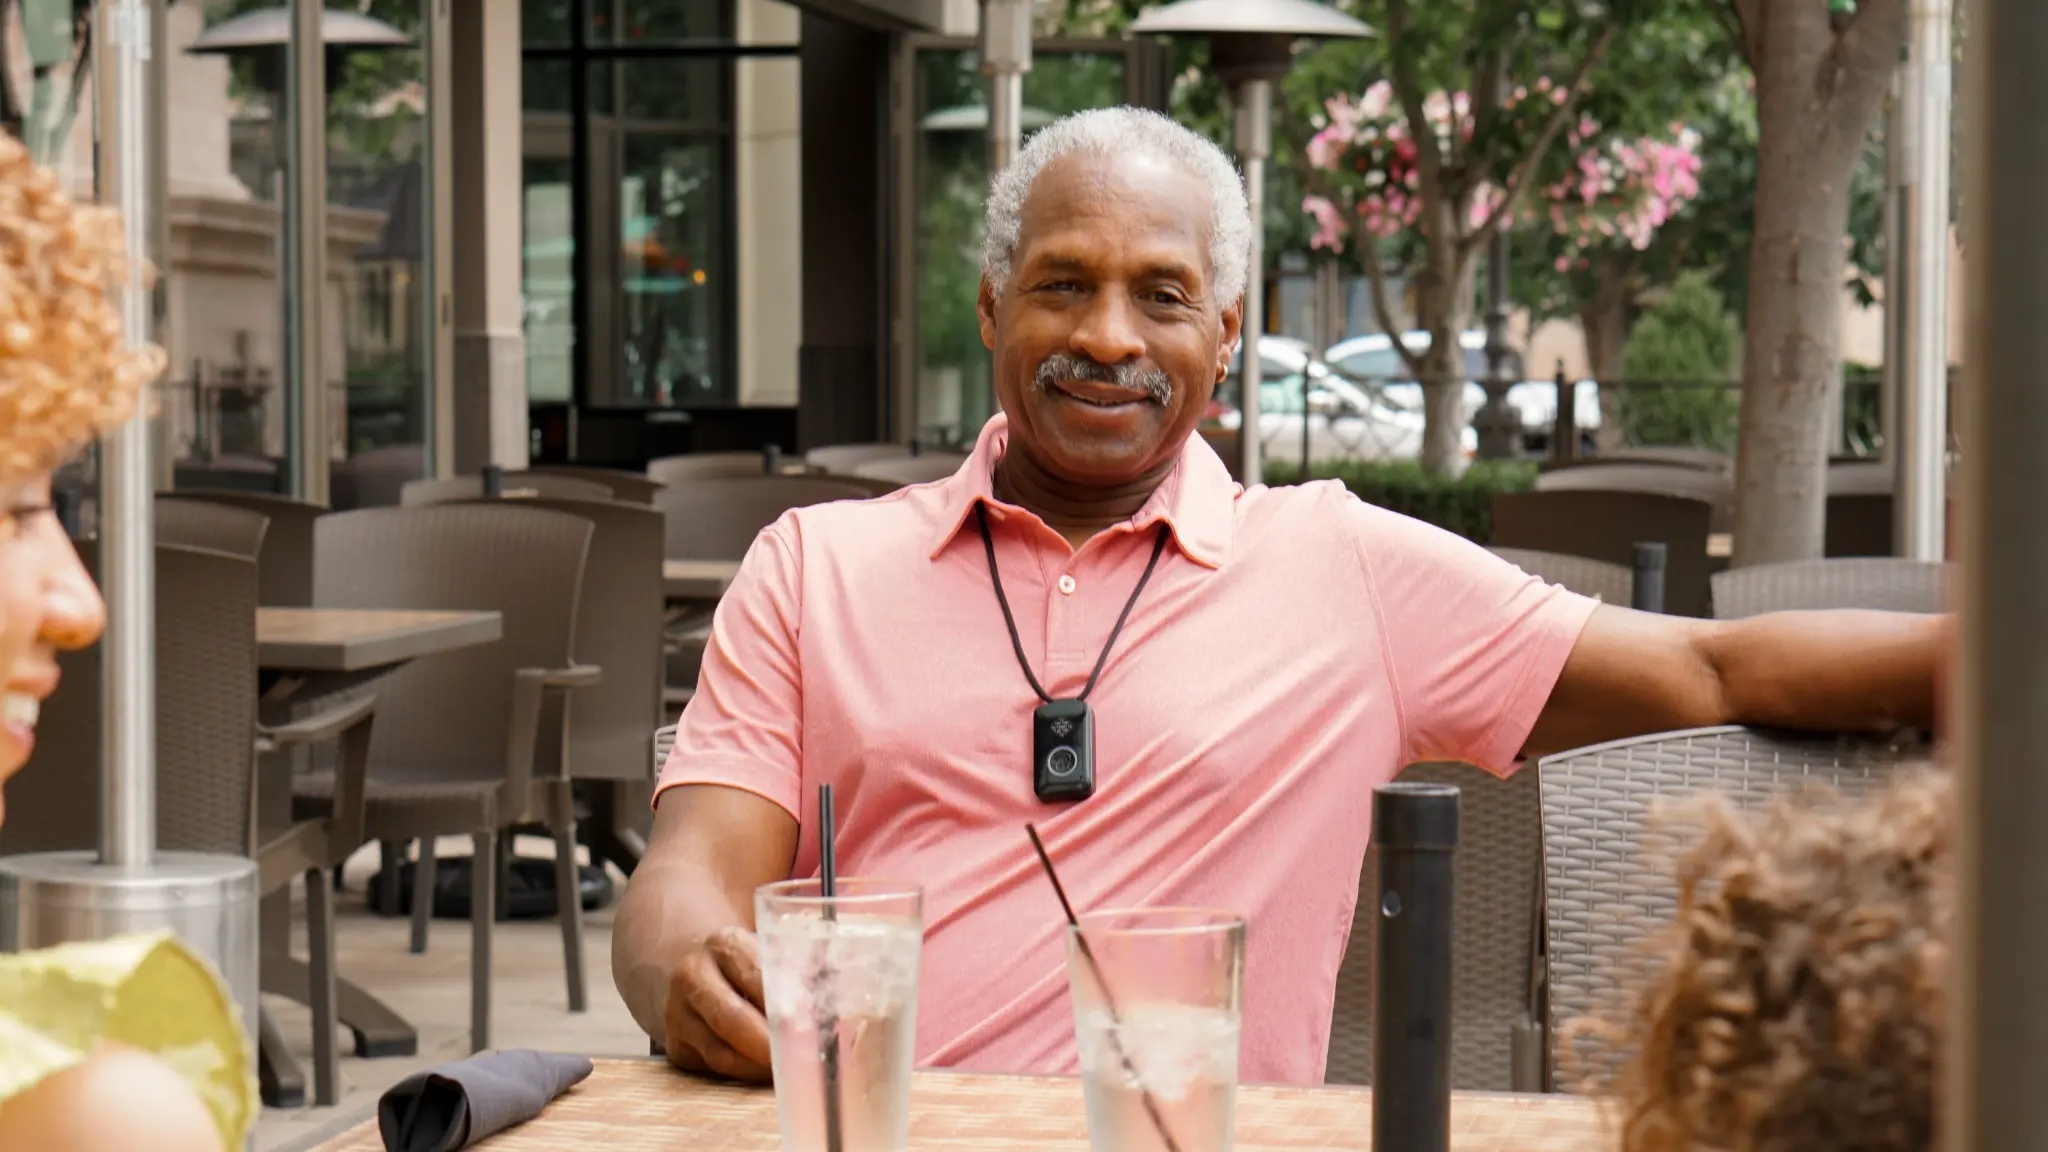
To be direct about our own product, Medicare does not cover medical alert systems, and we do not pretend otherwise. Some Advantage plans offer allowances that a member could potentially apply to safety equipment, but that varies by plan and by year and we will never tell you a specific plan covers it. What we can tell you is the actual price, which starts at $29.00 per month for the Home Link, month to month with no contract. The Cellular Home Link at $34.95 per month is the common choice for a parent who gave up their landline.
Confirm the Plan Is Even Being Offered Next Year
This is the check most people skip, and this year it is the one most likely to matter. A plan your parent has been happy with for six years is not guaranteed to exist in their county in 2027.
Several insurers are reducing their Medicare Advantage footprint or leaving certain counties entirely for the coming year, and Forbes reported in August that the pace of those exits is picking up. This is not cause for alarm and it is not a reason to rush into anything. When a plan is discontinued, members are notified and given a special enrollment period, so nobody is left without coverage.
It is simply the best argument for opening the September envelope. A discontinuation notice is easy to spot when you are reading and easy to miss when you are not. Fifteen minutes of reading in October beats a surprise in January.
Where to Get Free, Unbiased Help
California has a program built for exactly this, and it costs nothing. HICAP, the Health Insurance Counseling and Advocacy Program, provides free one on one counseling from trained volunteers who do not sell insurance and earn no commission. Every Bay Area county has a HICAP office, and appointments fill up during open enrollment, so book early through the California Department of Aging.
Your county Area Agency on Aging is the other door worth knowing, and it opens onto far more than insurance: meal programs, transportation, senior center activities, and caregiver support. The federal Eldercare Locator will find the right office by ZIP code, and SHIP is the national version of HICAP if your parent lives outside California. You can also call 1-800-MEDICARE directly, twenty four hours a day.
What all of these have in common is that nobody on the other end is paid based on what your parent enrolls in. That is the standard to hold any advice to, including advice about medical alert systems, and our post on how to choose a medical alert system is written with the same posture.
An October Conversation Worth Having in Person
Open enrollment tends to be the first time all year that an adult child sits down with a parent and looks carefully at how things are actually going. That is worth more than the plan comparison itself. If you are managing it from Seattle or Denver, our guide to long distance caregiving covers how to set up a house you cannot drop by.
October in the Bay Area gives you natural openings. Fleet Week brings the Blue Angels over the city and a lot of older residents stay in with the windows closed. Hardly Strictly Bluegrass fills Golden Gate Park and rearranges the traffic for a weekend. And on Halloween the doorbell rings all evening, which is a joy and is also a lot of standing up, walking to the door, and stepping back down again for someone whose balance has changed. Watching that once tells you more than any phone call.
Vital Link has been family owned in Oakland since 1981, working with hospital discharge planners, case managers, and Area Agencies on Aging across Alameda County and the eight counties around it. When a family decides a system makes sense, a local technician drives to the house, installs it, tests it, and trains everyone in the room. If the conversation with your parent is the hard part, our post on how to talk to a parent about a medical alert system is the place to start.
- Call us at (510) 338-3466
- Visit our contact page to schedule an in-home visit
- Serving Alameda, Contra Costa, Marin, Napa, San Francisco, San Mateo, Santa Clara, Santa Cruz, and Solano counties
Keep Reading
| Medicare Scams Targeting Seniors The fake coverage calls that spike every enrollment season, and how to shut them down. | Read More |
| Long Distance Caregiving How to set up a parent’s home when you live in another state. | Read More |
| The Cost of Aging in Place vs Assisted Living Real Bay Area numbers for the decision behind the paperwork. | Read More |
| Aging in Place Home Safety Checklist A room by room walkthrough for your next visit. | Read More |
Sources
- Medicare.gov: When Can I Join a Health or Drug Plan
- Medicare.gov: Medicare Plan Finder
- California Department of Aging: Health Insurance Counseling and Advocacy Program (HICAP)
- Administration for Community Living: Eldercare Locator
- SHIP National Technical Assistance Center: Find Local Medicare Help
- National Institute on Aging: Safe Use of Medicines for Older Adults
- Forbes: Thousands of Seniors May Lose Medicare Advantage as Plan Exits Escalate
Worried About More Than the Paperwork?
If this year’s review left you thinking about how your parent is managing alone, we are glad to talk it through with no pressure and no contract.
Frequently Asked Questions
When is Medicare open enrollment for 2027 coverage?
Medicare open enrollment runs October 15 through December 7, 2026. Changes made in that window take effect January 1, 2027. There is also a Medicare Advantage open enrollment period from January 1 through March 31 for people already in an Advantage plan.
What is the Annual Notice of Change and why does it matter?
The Annual Notice of Change is the document your parent’s plan mails by the end of September. It compares what the plan covers this year against what it will cover next year, including premiums, copays, the drug list, the provider network, and supplemental benefits. It is the fastest way to find out whether anything needs attention.
Does my parent have to do anything during Medicare open enrollment?
No. If the plan is still offered and nothing important is changing, doing nothing means the coverage renews automatically. The point of reviewing is to confirm that, not to force a switch. Most years, no change is the right answer.
Where can we get free help comparing plans in the Bay Area?
California’s HICAP program offers free one on one counseling from trained volunteers who do not sell insurance and earn no commission, with an office in every Bay Area county. Your county Area Agency on Aging and 1-800-MEDICARE are also free. Appointments fill up during open enrollment, so book early.
What if my parent’s Medicare Advantage plan is discontinued for 2027?
They will be notified, and they receive a special enrollment period to choose new coverage, so nobody is left without insurance. Several insurers are reducing their Medicare Advantage footprint for 2027, which is a good reason to read the September notice rather than assume next year matches this year.
Does Medicare cover a medical alert system for a parent living alone?
No. Original Medicare does not cover medical alert systems. Some Medicare Advantage plans offer supplemental allowances that vary by plan and by year and could potentially apply, so check the plan documents directly. With Vital Link, systems start at $29.00 per month, month to month with no contract, and in-home setup by a local technician is included.